Personal finance · Debt repayment
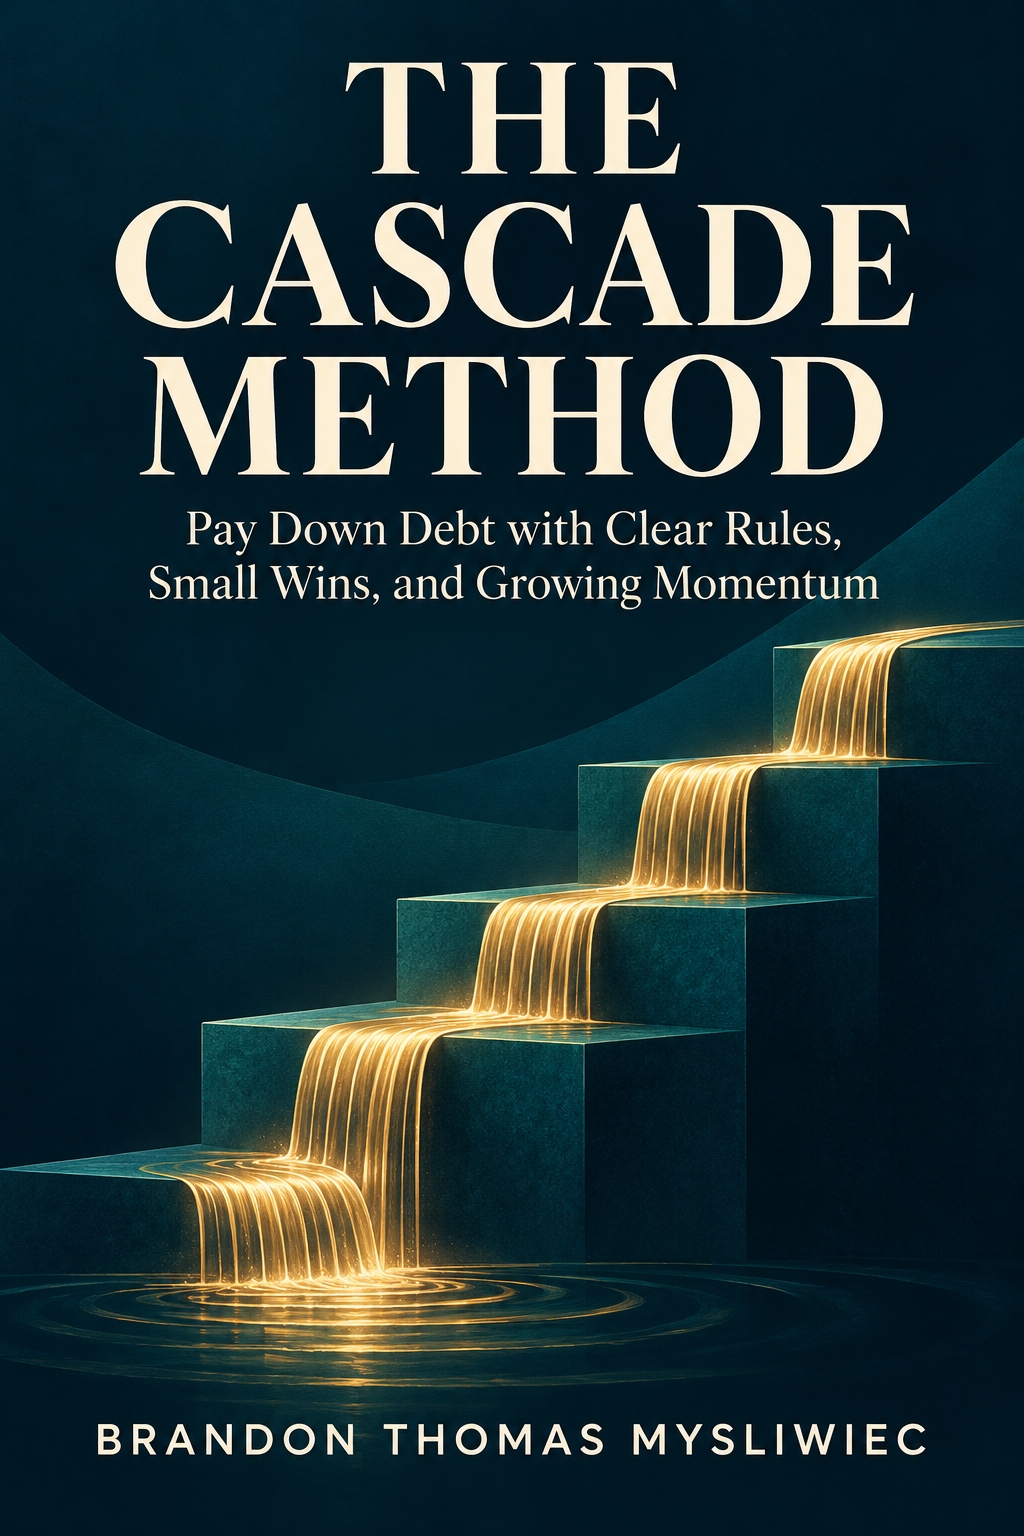
The Cascade Method
Pay Down Debt with Clear Rules, Small Wins, and Growing Momentum
By Brandon Thomas Mysliwiec
A mortgage. Car loans. Student loans. Credit cards. Small purchase plans. When every account wants a payment, knowing where to start can be the hardest part.
The Cascade Method gives your next available dollar a clear job, with a practical routine for choosing a target, finishing smaller balances, and keeping payments moving.
Paperback and digital publication details will be added here.
The repayment routine
Three clear rules
Highest APR by default
Fund required payments first. Direct extra money to the eligible balance with the highest interest rate.
A complete smaller payoff when it fits
If your remaining extra can finish a smaller eligible balance, pay it in full. Recheck what remains, then return to the highest APR when another complete payoff does not fit.
Full rollover of freed payments
Keep the affordable total debt budget working. When an obligation finishes, its freed payment becomes part of the next month’s extra.
A complete household picture
Examples that include the whole debt list
The main fictional household has twenty separate accounts: a $250,000 mortgage, two $25,000 cars, eight semester student loans between $5,000 and $10,000 each, four credit cards between $2,500 and $5,000 each, and five consumer balances between $180 and $1,200.
The book compares Cascade, Snowball, and Avalanche using the same debts and payment budget. It follows early payoffs, total interest, and the later milestones—and shows how a smaller affordable payment changes the journey.
Business examples and counterexamples show the tradeoffs. A smaller payoff can cost more interest than following Avalanche. Your actual loan terms, benefits, and affordable budget matter.
From reading to a monthly practice
Seven worksheets, one repeatable routine
Build a debt map with room for twenty accounts. Find your affordable extra, check dates and special terms, assign payments, verify postings, record progress, and plan the next stage.
Fourteen chapters explain the decisions in plain language, with worked examples, charts, checklists, and a first-90-days action plan. The goal is a payment routine you can maintain without borrowing again for essentials.
About the author
Brandon Thomas Mysliwiec
An entrepreneur, business owner, and financial innovator, Brandon presents Cascade as a practical framework for clear payment decisions, visible progress, and disciplined rollover.